
Basic Bookkeeping Principles — Part 2

In Part 1 of Basic Bookkeeping Principles, we discussed the type of accounts used in bookkeeping, what debits and credits are, the use of double entries, the use of T-Accounts to help with the process of raising journal entries, the general ledger and what a trial balance is.

The examples of the entries we processed in Part 1 were mainly cashflow items — meaning that they either credited or debited the bank account. There are, however, other adjusting journal entries (non-cashflow items) that are raised in the books of a company such as: depreciation, accruals, provisions, prepayments, revaluation of assets, etc.
Here are some examples:
Accruals
Although accruals generally will be the exact amount of a quote or order, it can also be a fairly accurate estimate if the exact amount is not known. Accruals are made where expense items are purchased but either not yet invoiced by the supplier, or terms were agreed upon for payment later. The items are, however, received and used in a specific month. To not show an inflated profit in a specific month, all expenses relating to that month, that have not yet been processed in the books, should be accrued for.
Example:
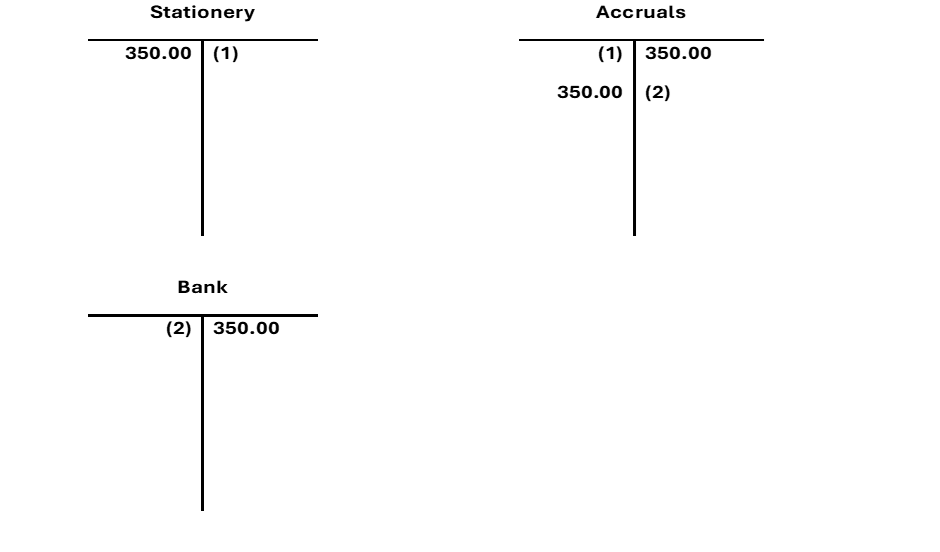
An order was issued for the purchase of stationery for 350.00, it was received and used in that month (transaction 1), but the payment was only processed the following month (transaction 2).
Depreciation
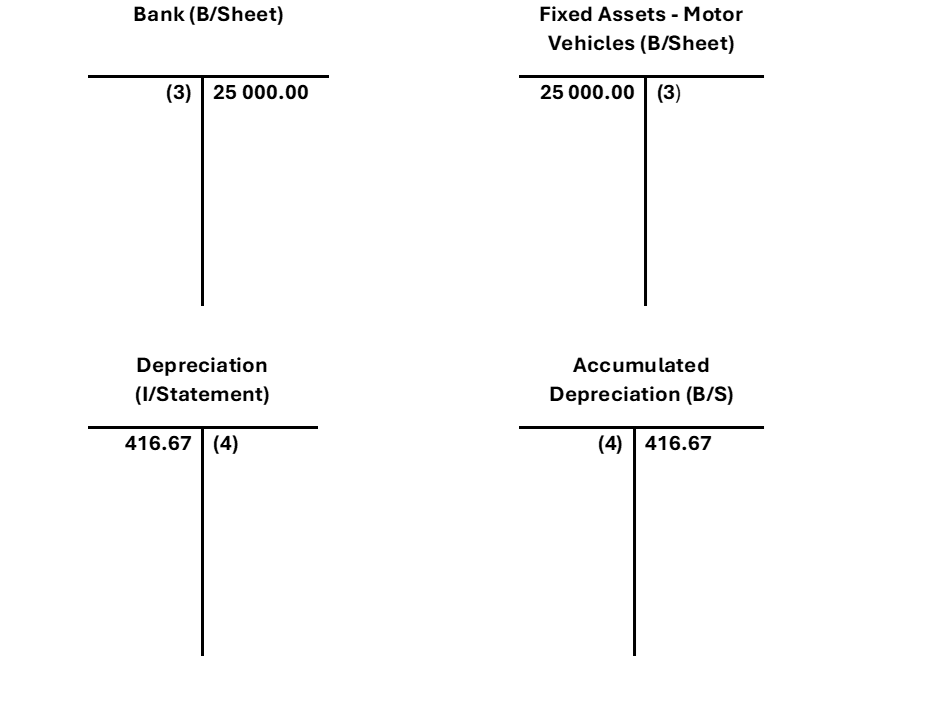
When purchasing a fixed asset item such as a motor vehicle, then provision must be made for the value it loses every month — this is called depreciation. Let’s say a vehicle is bought for 25 000.00 (transaction 3) and the asset is written off (depreciated) over 5 years, therefore, 20% per annum. The monthly depreciation will be 25 000 x 20% divided by 12 months = 416.67 (transaction 4). At any given time, the net asset value (NAV) of the motor vehicle will be the cost price less the accumulated depreciation.
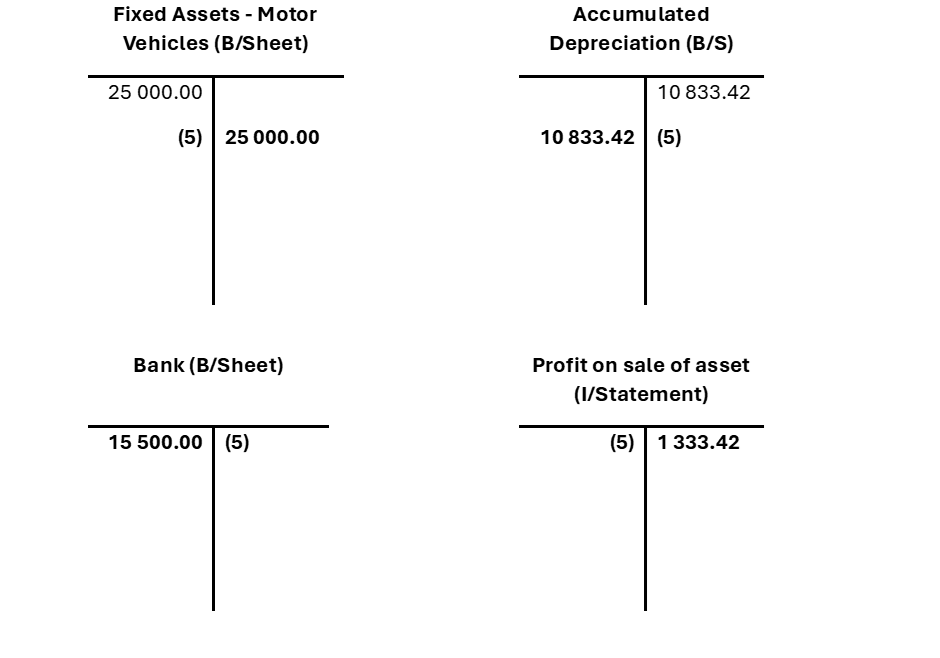
For this example, let’s assume that the company decides to sell the motor vehicle after 26 months for an amount of 15 500. The following journals will be passed: Note that the accumulated depreciation account would have a balance of 10 833.42 that would have been provided over the 26 months (416.67 x 26). The NAV of the vehicle is therefore, 14 166.58. The selling price is 15 500 and a profit is realized on the sale of the vehicle of 1 333.42.
Provisions
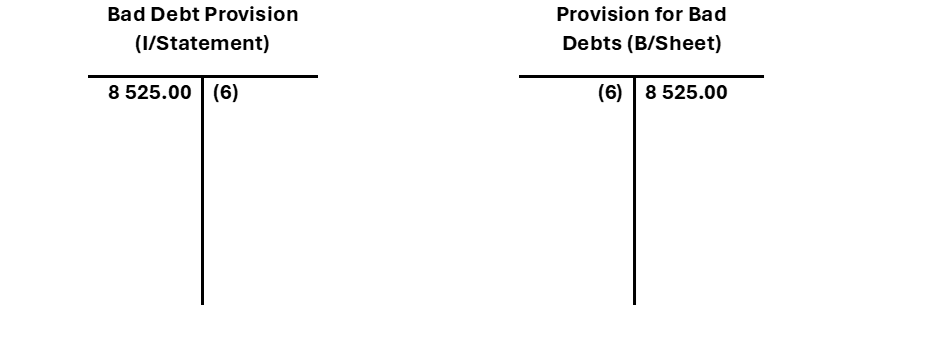
It may also be prudent to make certain provisions for occurrences, such as bad or doubtful debts. Let us assume the company has an outstanding debtors account balance of 110 000.00. Of this amount, 80% is within the normal 30-day period, 15% is within the 60-day period and 5% more than 60 days. The company’s risk policy may be to provide for 25% of the outstanding balance of the 60-day period and 80% of the outstanding balance of the 60-day plus amount as potential write-offs. Therefore, 110 000 x 15% x 25% = 4 125.00 plus 110 000 x 5% x 80% = 4 400.00 — a total provision of 8 525.00 (transaction 6).
Prepayments
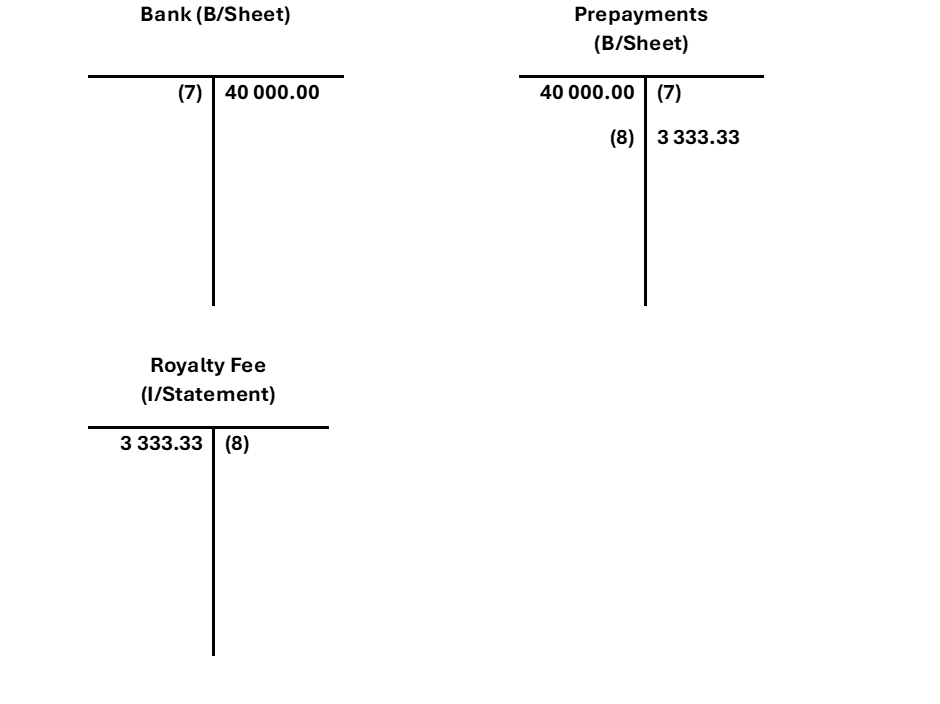
A prepayment occurs when a large amount is paid in advance. In this case let us assume that the company must make an annual payment of 40 000.00 for royalties for the coming year. It would, therefore, not make sense to expense the full amount in the month that is paid but to rather smooth it out over the following 12 months. The entry would thus be to divide 40 000.00 by 12 months = 3 333.33 per month (transactions 7 & 8).
Revaluation of Immovable Fixed Asset
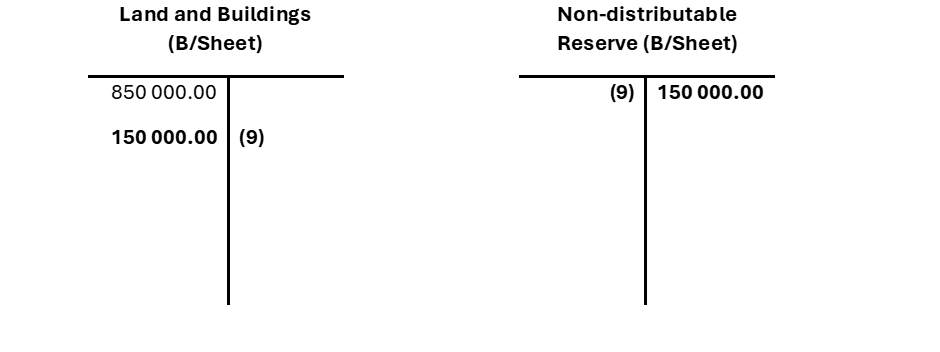
It may happen that the owners decide to have a valuation done on the office premises that they own to reflect a more accurate value on the balance sheet. We know that the value of a movable asset diminishes over time and that is why we make provision for depreciation. However, land, and the buildings thereon, increase in value over time and this need to be reflected in the books of the company. Let us assume that the company bought their premises 10 years ago but has not had a valuation done since then and the purchase price was 850 000.00. A subsequent valuation by a registered valuator places a new value of 1 000 000.00 on the premises (transaction 9). There is thus a “potential profit” of 150 000.00. This is also called an unrealized profit because the actual profit will only realize when the premises are sold. To reflect this correctly on the balance sheet, the unrealized profit is credited to a Non-distributable Reserve Account (NDR). This means that, although this is reflected under the equity of the owners, it cannot be distributed or paid to the shareholders as the profit has not been made yet.
So, this is what bookkeeping is all about! Once you understand the different types of accounts and their balances, the concept of using T-Accounts to ascertain the correct journals to process, and that expenses and revenue are shown in the correct month to which it pertains (accruals and prepayments), then you are good to go! A final checklist is to ensure that the debit and credit balances of all your accounts are equal (Trial Balance). Although, as mentioned before, if accounting software is used, it will ensure that your journals will always balance and therefore your accounts will also be in sync.
If you have any questions, then please contact us here.
Comments